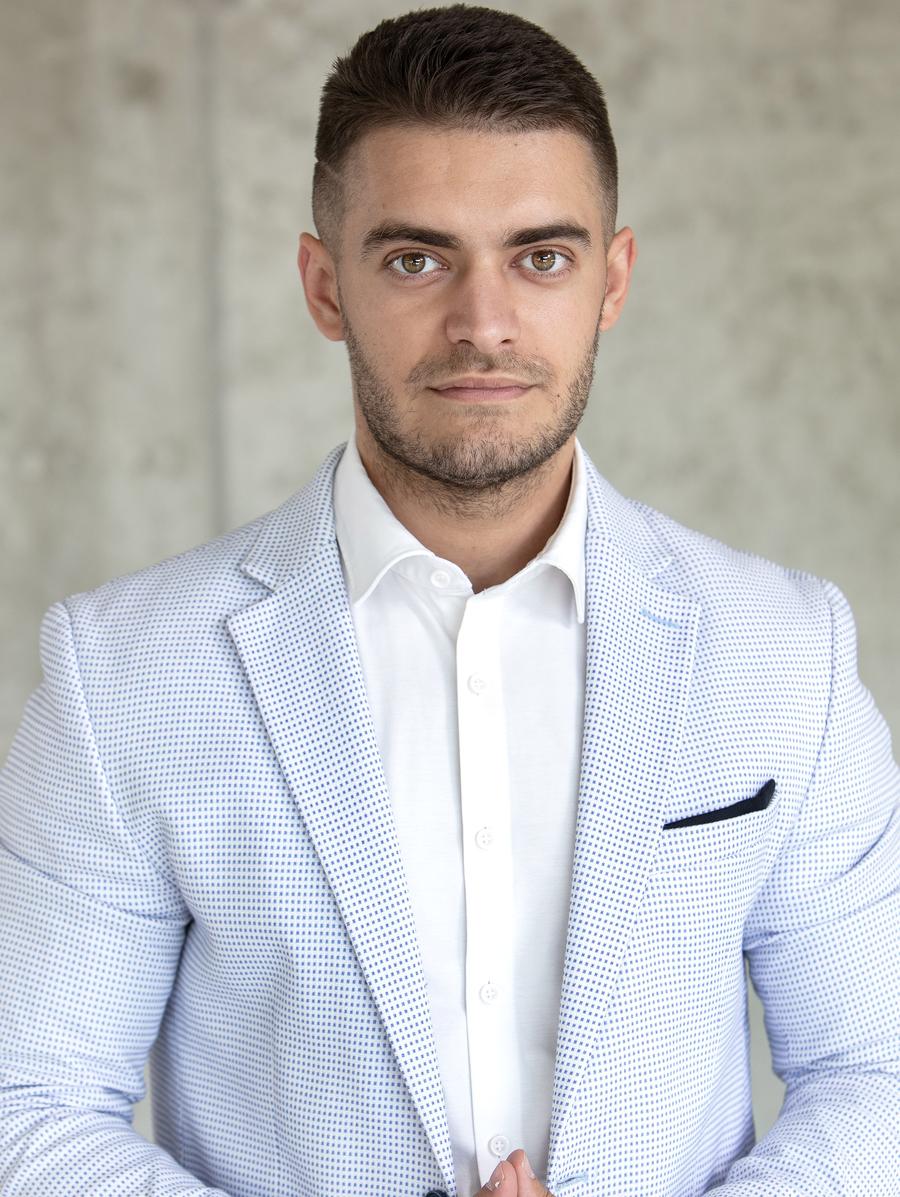
Ábel Dudás
One road leads to wealth. And an entirely different one to keeping it.
For me, protecting wealth is not just a professional conviction. It was born of a personal story.
Personally
“I was only about three years away from being secure for the rest of my life.” — my father
The sentence that stayed with me
My father was a successful entrepreneur.
Things went well. Then the situation changed. I remember one conversation. He told me:
“I was only about three years away from being secure for the rest of my life.”
In the end his business collapsed and he fell into serious financial difficulties from which he has never fully recovered. That sentence gave me no peace. I began to search for where the mistake had been made. Why do some people who started with less end up keeping more? How can a family's security, built over years, be lost so quickly? And what do those whose wealth survives crises and generations do differently?
That curiosity led me to finance and to wealth management.
I understood that it is not enough to know how to earn money. You have to know how to protect it, allocate it correctly and prepare it to fulfil its role between the cycles of life.
What to invest in?
Investing is not the goal. It is a tool.
When people ask me about investing, they usually want to know one thing: what to invest in? In my view, that is only the second question. The first should be: what life do I want to live?
People do not want more money for its own sake. They want the freedom money can give them. The freedom to spend more time with their family. To help their children. To decide freely when and what to do. Not to decide out of necessity in a bad economic period. To choose how much they work and what life they live. To secure their children's future.
That is why, for me, a financial strategy does not begin with funds, shares or products. It begins with questions.
Only after the answers does it make sense to talk about a specific investment strategy.
Business and life
The business has a strategy. Private life often does not.
Over the years I have spoken with many successful entrepreneurs. They know exactly what revenue, growth or market position they want to achieve. But when I ask them about their personal goals, silence often follows.
Yet a business cannot be a financial plan in itself. It can be the most important engine of wealth — but it is often also its greatest risk. If the family's income, a significant part of the wealth and the hope of a future exit all come from the same business, these are not three different sources. It is the same risk in three forms.
The goal is not to take the wind out of the business. The goal is to gradually build, alongside it, wealth that does not depend on the same economic cycle, country, industry or the owner's personal presence.
Two skills
Building wealth and keeping it are two different skills.
Building wealth often rewards concentration, courage, optimism and fast decisions. Keeping wealth requires diversification, humility, healthy caution, rules and preparedness.
This is not a contradiction. The role of money changes with the life situation. What was a justified risk in the growth phase can later become a dangerous dependence.
The real risk
The greatest risk is not market movement.
We often equate risk with a single number: how much the price of an investment can fluctuate. For me the more important question is what can derail the plan for good.
A forced sale at the wrong time. Too little liquidity. Wealth built on a single business or a single property market. A loan that swallows room for manoeuvre in a worse period. A product whose costs or workings we do not understand. Or an emotional decision made out of fear or euphoria.
We cannot control market movements. Diversification, costs, liquidity, structure and our own decision rules — those we can.
Strategy and emotions
Strategy also protects us from our own emotions.
Human beings are emotional. In good times they easily believe that growth will last forever. In a crisis they easily doubt even what they built correctly in calm conditions.
A good strategy is therefore not only about what to buy. It also defines the role of every part of the wealth, when to rebalance, how much liquidity is needed, when to gradually reduce risk — and what to do when the market falls sharply.
Rules must be created in calm times. In a crisis, all that remains is to follow them.
Preparedness, not prophecy
A quality financial strategy is not built on predicting the future. It is built on preparedness.
Nobody knows for certain what the next year, the next crisis or the next stage of life will bring. A good strategy therefore does not rest on a single forecast.
It prepares for several possible futures. It reckons with markets falling, interest rates changing, the business entering a harder period and life goals transforming.
Not every risk needs to be eliminated. You need to know exactly which risk you are taking and why, which you are reducing, which you are insuring and for which you are building adequate liquidity.
What wealth management means to me
Not more products. An understandable system.
Not just building a portfolio. But a plan for connecting money with the life the client wants to live.
Not as many products as possible. But an understandable system in which every decision has a clear reason.
Not short-term reactions to the market. But rules that show the direction even when emotions dictate otherwise.
Not one successful investment year. But the long-term protection of the family's goals, freedom and wealth.
Good wealth management is ultimately about money supporting the life you have chosen — and not about adapting your life to money.
Professional background
Qualifications and experience
A professional qualification recognised across Europe, built on the aligned management of financial planning, investments, risks and the client's interest.
EFA — European Financial Advisor
A professional qualification recognised across Europe, built on the aligned management of financial planning, investments, risks and the client's interest.
Almost ten years of experience in finance
Experience in wealth planning, investments, financing and long-term client relationships.
Slovak, Hungarian and English
Personal communication in three languages, according to the needs of the family and the experts involved.
Independent financial advice
Remuneration comes exclusively from our clients.
Next step
Let us talk about your situation.
A short phone or online conversation — no commitment, no product presentation.